

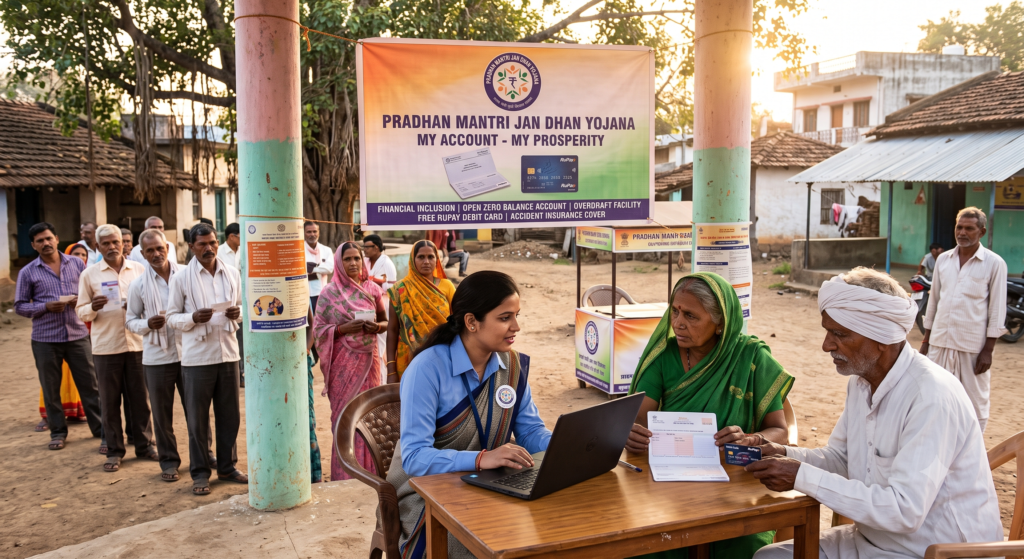
Pradhan Mantri Jan Dhan Yojana (PMJDY) is a major financial inclusion initiative of the Government of India. The scheme was introduced to make banking and other financial services accessible to people who previously had limited or no access to formal banking facilities.
Through PMJDY, eligible individuals can open a basic bank account and access services such as deposits, money transfers, debit cards, and access to government benefit transfers. The scheme is an important part of India’s effort to connect economically weaker and underserved sections of society with the formal financial system.
What is Pradhan Mantri Jan Dhan Yojana?
Pradhan Mantri Jan Dhan Yojana is a national financial inclusion programme launched on 28 August 2014. Its main objective is to ensure that every eligible household has access to a bank account and basic financial services.
The programme focuses particularly on people who do not have regular access to banking services.
Main objectives of PMJDY
The key objectives include:
- Providing access to basic banking facilities.
- Encouraging people to save money through formal banking channels.
- Making money transfers easier and safer.
- Supporting Direct Benefit Transfer (DBT) of eligible government benefits.
- Providing access to basic financial products.
- Promoting financial literacy.
- Bringing underserved sections of society into the formal financial system.
- Encouraging the use of digital payment and banking services.
Key Features of PMJDY
PMJDY accounts provide several important banking facilities. The exact benefits and eligibility conditions can depend on applicable government and banking rules.
1. Basic Bank Account
An eligible person can open a basic savings bank deposit account under PMJDY through participating banks and banking channels.
The account is designed to provide essential banking services to people who may not previously have had access to a bank account.
2. Zero-Balance Facility
A major feature of PMJDY is that the basic account can be maintained without a minimum balance requirement, subject to the applicable account terms.
This makes formal banking more accessible to people with limited or irregular income.
3. RuPay Debit Card
PMJDY account holders may receive a RuPay debit card, subject to the applicable banking terms.
The card can be used for eligible transactions through supported ATMs, point-of-sale terminals and other participating payment channels.
4. Direct Benefit Transfer
PMJDY accounts can be used for receiving eligible government benefits through Direct Benefit Transfer (DBT).
Instead of relying entirely on cash-based distribution, eligible benefits can be transferred electronically to a beneficiary’s bank account when the relevant scheme and account conditions allow it.
5. Access to Other Financial Services
PMJDY is not limited to opening a bank account. It is intended to connect account holders with other financial services, including suitable insurance, pension and credit-related products, subject to eligibility and applicable rules.
6. Overdraft Facility
Eligible PMJDY account holders may be able to access an overdraft facility, subject to the prevailing government and bank rules, account history and eligibility conditions.
The overdraft facility should not be considered automatic for every account holder.
Who Can Open a PMJDY Account?
PMJDY is primarily intended to provide banking access to people who do not have adequate access to formal banking services.
Generally, an eligible individual can approach a participating bank or banking outlet to enquire about opening a PMJDY account.
Before opening an account, the bank will verify the applicant’s identity and other required information according to applicable banking and KYC rules.
Important points
- The applicant should meet the applicable account-opening requirements.
- KYC requirements must be completed.
- Existing bank accounts and the individual’s banking circumstances may affect how the account is opened or categorized.
- Specific benefits are subject to the current rules and eligibility criteria.
Documents Required for PMJDY Account
The documents required can vary depending on the applicant and the bank’s applicable KYC procedures.
Commonly required information or documents may include:
- Aadhaar, where applicable and accepted for KYC.
- Another officially valid document, where required.
- Proof of address, where applicable.
- Passport-size photograph, depending on the bank’s requirements.
- Mobile number, if available and required for banking services.
Applicants should confirm the current document requirements with the participating bank before visiting the branch.
How to Open a PMJDY Account
Opening a PMJDY account generally involves the following steps:
Step 1: Visit a participating bank
Visit a bank branch or banking outlet offering PMJDY services.
Step 2: Ask for a PMJDY account
Tell the bank representative that you want to open an account under Pradhan Mantri Jan Dhan Yojana.
Step 3: Complete the application form
Fill in the account-opening form with accurate personal and contact information.
Step 4: Submit KYC documents
Provide the required KYC documents and information requested by the bank.
Step 5: Verification
The bank will verify the submitted information according to applicable rules.
Step 6: Account activation
After successful verification and account-opening formalities, the bank will provide the account details and applicable banking facilities.
Step 7: Debit card and other services
If applicable, the account holder can receive a RuPay debit card and access other available services according to the bank’s terms.
Benefits of Pradhan Mantri Jan Dhan Yojana
PMJDY can provide several benefits to eligible account holders.
Major benefits include:
- Access to formal banking services.
- Ability to deposit money safely in a bank account.
- Easier electronic transfer of money.
- Potential access to government benefit transfers.
- RuPay debit card facility, subject to applicable terms.
- Access to eligible overdraft facilities.
- Opportunity to connect with insurance and pension products.
- Greater awareness of formal financial services.
- Reduced dependence on informal financial channels.
- Support for digital banking and payments.
PMJDY and Financial Inclusion
Financial inclusion means making useful and affordable financial services available to individuals and communities that have traditionally had limited access to banking.
PMJDY contributes to financial inclusion by bringing more people into the formal banking network.
A bank account can also act as an important foundation for accessing other financial services. For example, people can use formal banking channels to receive money, save funds, make payments and potentially access eligible financial products.
PMJDY and Digital Banking
The expansion of digital banking has changed how people manage their finances. PMJDY accounts can support the broader use of electronic banking and digital payment systems.
Depending on the facilities available through the bank, customers may be able to use:
- ATM services.
- Debit card transactions.
- Electronic fund transfers.
- Mobile banking.
- Internet banking.
- Other supported digital payment services.
Customers should follow their bank’s security instructions and never share their PIN, OTP, password or other confidential banking information with anyone.
PMJDY and Government Schemes
A bank account can be important when government schemes use bank-based payment systems.
Eligible beneficiaries of various government programmes may receive benefits directly into their bank accounts when DBT is applicable and the required conditions are satisfied.
However, opening a PMJDY account does not automatically make a person eligible for every government scheme. Each government scheme has its own eligibility criteria, application process and benefit conditions.
Difference Between PMJDY and a Regular Savings Account
PMJDY is specifically designed as a financial inclusion initiative. A regular savings account can have different eligibility requirements, minimum-balance conditions, charges and features depending on the bank and account type.
Some important differences may include:
| Feature | PMJDY Account | Regular Savings Account |
|---|---|---|
| Main purpose | Financial inclusion | General banking and savings |
| Minimum balance | Basic PMJDY accounts generally have no minimum balance requirement | Depends on bank/account type |
| Target group | People with limited access to banking | General customers |
| RuPay card | Available subject to applicable terms | Depends on account |
| DBT | Can support eligible DBT payments | Can also support eligible DBT |
| Other financial products | May provide access subject to eligibility | Depends on bank/account |
Important Things to Remember
Before opening or using a PMJDY account, customers should remember the following:
- Always provide accurate information to the bank.
- Complete the required KYC process.
- Keep your mobile number updated with the bank where appropriate.
- Never share your ATM PIN or OTP.
- Check bank messages and account statements regularly.
- Report unauthorized transactions immediately.
- Understand applicable charges and account terms.
- Keep your debit card secure.
- Contact the bank for clarification if an expected benefit or transaction has not been received.
Frequently Asked Questions About PMJDY
What is PMJDY?
PMJDY stands for Pradhan Mantri Jan Dhan Yojana. It is a Government of India financial inclusion programme designed to expand access to basic banking services.
When was PMJDY launched?
Pradhan Mantri Jan Dhan Yojana was launched on 28 August 2014.
Can a PMJDY account be opened with zero balance?
The basic PMJDY account is designed to be operated without a minimum balance requirement, subject to the applicable account terms.
Does every PMJDY account automatically receive an overdraft?
No. An overdraft facility is subject to eligibility requirements and the applicable rules of the scheme and bank.
Can PMJDY accounts receive government payments?
Yes, an eligible PMJDY account can be used for receiving eligible government benefits through DBT when the relevant scheme and account conditions are fulfilled.
Is a RuPay card available with PMJDY?
RuPay debit card facilities are associated with PMJDY accounts, subject to applicable eligibility and banking terms.
Can I use a PMJDY account for digital payments?
Depending on the facilities enabled by the bank, customers may be able to use debit cards, mobile banking, electronic transfers and other supported digital payment services.
Conclusion
Pradhan Mantri Jan Dhan Yojana (PMJDY) has played an important role in expanding access to formal banking services in India. By providing a pathway to basic bank accounts and connecting eligible customers with services such as digital payments, DBT and other financial products, the programme supports the broader goal of financial inclusion.
For anyone interested in opening a PMJDY account, the best approach is to visit a participating bank and confirm the latest eligibility requirements, documents, benefits, charges and available facilities before applying.
Disclaimer: This article is provided for general informational purposes. PMJDY benefits, eligibility criteria, banking facilities and applicable rules may change. Readers should verify the latest information through official Government of India or participating-bank sources before taking any financial or banking decision.


